
Successive Money Laundering
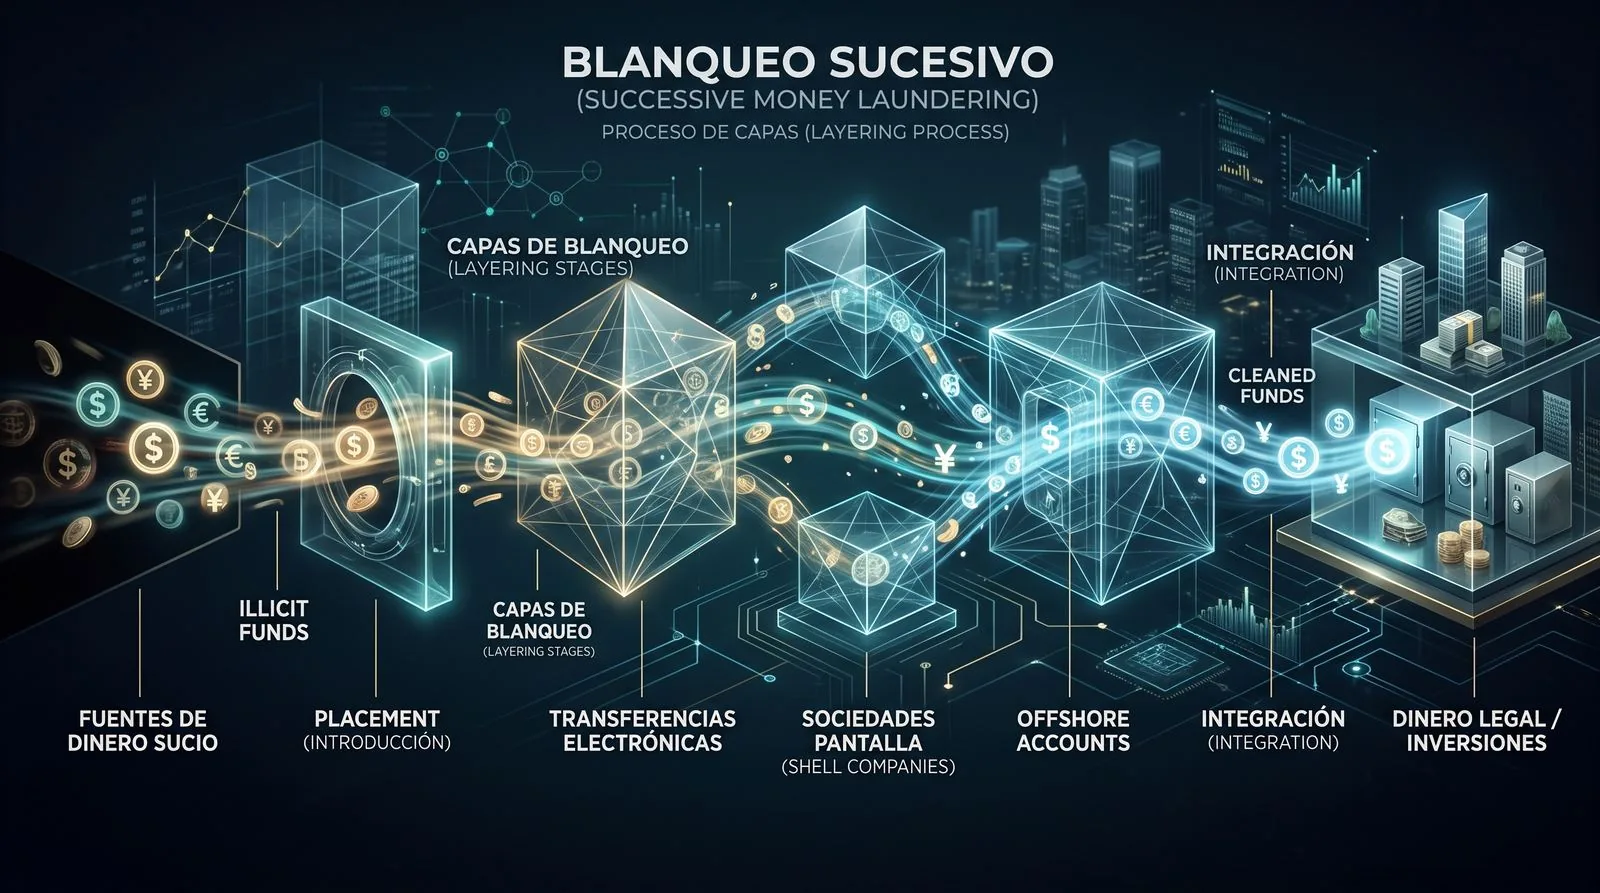
1. What is successive money laundering?
Article 301.2 of the Criminal Code punishes anyone who conceals or disguises the true nature, origin, location, destination, movement or rights over assets, or their ownership, knowing that they come from one of the offences referred to in the preceding paragraph or from an act of participation in them.
Reading both paragraphs together reveals a tiered architecture that forensic practice often overlooks:
Article 301.1 CP punishes conduct carried out over assets that come directly from a prior criminal activity (the predicate offence: drug trafficking, corruption, tax fraud, unfair administration, human trafficking…).
Article 301.2 CP punishes conduct carried out over assets that come from a prior act of laundering. In other words, the material object of the offence is no longer the raw proceeds of the predicate offence, but a product that has already been laundered, transformed or reconverted.
Hence the formula that has become established in legal doctrine and case law: successive laundering is the "laundering of what has already been laundered."
Contamination as a transitive property of the estate
The dogmatic key — and the one that explains the enormous potential scope of the offence — is that the illegality is not exhausted in the first laundering operation. The laundered asset remains contaminated and in turn contaminates everything that derives from it. The chain propagates:
Predicate offence → 1st transformation (original laundering, art. 301.1) → 2nd, 3rd, nth transformation (successive laundering, art. 301.2) → returns, fruits and subrogated assets.
This also covers subrogated assets and the returns generated while the structure remains operative: the rent from a property acquired with contaminated funds, the capital gain on its sale, the shareholdings subscribed with those proceeds. Even where the specific asset is acquired with money coming from investments that no longer bear a direct arithmetical relation to the original criminal gain, the prosecution will argue that the unlawful connection subsists.
💡 KEY POINT FOR THE DEFENSE
That propagation is neither infinite nor automatic. This is precisely where the defense effort must be concentrated: contamination is asserted, but it must also be proven. When the Public Prosecutor invokes the unlawful connection without reconstructing the intermediate link, it is substituting proof of origin with a presumption of continuity. And a presumption of continuity is not evidence of guilt.
2. The guiding case: STS 299/2021 and the conviction of "Sito Miñanco"
The mandatory reference ruling in this area is the Judgment of the Supreme Court (Criminal Chamber, 1st Section) No. 299/2021, of 8 April (Reporting Justice: Excmo. Sr. D. Javier Hernández García; ROJ: STS 1236/2021 | ECLI:ES:TS:2021:1236).
The facts
The Supreme Court decided the appeal in cassation against the judgment of the 2nd Section of the Provincial Court of Pontevedra, which convicted José Ramón Prado Bugallo — "Sito Miñanco" — his first wife, his daughter and a businessman for laundering proceeds of drug trafficking. The case originated from preliminary proceedings opened in 2009 by the Court of Preliminary Investigation No. 2 of Cambados.
The proven facts describe a textbook model: an organised structure, built on intense personal and family ties, which over a prolonged period — between the late 1980s and 2012 — channelled funds linked to prior drug trafficking activities through two instrumental companies used to conceal and repatriate the proceeds.
The doctrine
The judgment is relevant to the criminal practitioner for four reasons:
It expressly establishes the category of successive laundering and the logic of transitive contamination: the laundered asset remains contaminated and transmits that condition to whatever derives from it.
It squarely addresses the evidentiary difficulties that arise when the activity is "juridified" through the interposition of corporate entities in the repatriation circuit and, moreover, extends over decades.
It acquits one of the defendants — the former sister-in-law — because the facts attributed to her were not conclusive and raised a reasonable doubt. It is a reminder that belonging to the launderer's family circle is not a self-sufficient indication.
It recognises undue delays and reduces the sentence from four years to three years and nine months' imprisonment, with a fine of five million euros, in addition to confirming the definitive closure of the instrumental company that operated as the hub of the scheme and ordering the confiscation of all the assets identified in the proven facts.
⚠️ A CRITICAL READING
STS 299/2021 is often cited as a "pro-prosecution" ruling because of how it formulates successive contamination. That reading is incomplete. The same ruling acquits a defendant for insufficient circumstantial evidence and reduces the sentence for undue delays in a case that dragged on for twelve years. The precedent is as useful to the defense as it is to the Prosecution: whoever invokes only its first half is giving up the second.
A second scenario: laundering of assets from a prior conviction for laundering
Also worth citing is STS 982/2021, of 15 December (Reporting Justice: Excmo. Sr. D. Vicente Magro Servet), rendered in cassation against a judgment of the 3rd Section of the Criminal Chamber of the Audiencia Nacional (abbreviated proceedings investigated by the Central Court of Preliminary Investigation No. 6). The case is paradigmatic of the figure: the conduct concerns assets linked to a person previously convicted by plea agreement both for an offence against public health and for money laundering, in facts dating from 2001-2002. In other words, the material object of the second proceeding was not the raw proceeds of drug trafficking, but the remainder of a laundering operation already adjudicated.
3. Multiple perpetrators: the successive launderer is not the original launderer
One of the structural features of successive laundering is subjective plurality. Several launderers may act on the same unlawful source, at different times and without prior agreement among them.
The usual pattern is as follows: a first person carries out the initial laundering operation and, to sustain the process over time, turns to third parties — nominees, administrators of shell companies, professional advisers, relatives — who carry out the subsequent transformations through the purchase of companies, the acquisition of real estate or the subscription of financial products.
This has three procedural consequences of the first order:
Identity of authorship is not required. Whoever carries out the successive laundering need not have taken part in the original laundering, still less in the predicate offence.
Intent must be proven individually for each participant. Knowledge of the criminal origin — even on the basis of dolus eventualis — is a typical element that must be proven with respect to each defendant, not with respect to the scheme as a whole. Mechanisms of collective imputation based on membership of the family or corporate group are constitutionally unacceptable.
The negligent form under art. 301.3 CP requires gross negligence. The breach of the duty of care must relate to the possibility of knowing the criminal nature of the assets, and must reach the threshold of gross or reckless negligence. The slight negligence of a professional who takes part in the transaction is not typical.
The boundary with self-laundering
A different question, although frequently confused in indictments, is that of self-laundering: the laundering of one's own proceeds by the perpetrator of the predicate offence. Its punishability was settled by the Resolution of the Non-Jurisdictional Plenary Session of the Second Chamber of the Supreme Court of 18 July 2006 (Acuerdo del Pleno no jurisdiccional de la Sala Segunda del Tribunal Supremo, a non-jurisdictional plenary sitting held to unify case-law criteria outside any specific case), under which Article 301 CP does not, in every case, exclude concurrence with the predicate offence — a criterion later confirmed by the reform introduced by Organic Law 5/2010, of 22 June.
Subsequent case law, however, has built significant interpretative limits to avoid double jeopardy (bis in idem) and excessive punishment:
STS 265/2015, of 29 April, clarifies that the typical conduct does not consist merely in acquiring, possessing or using the proceeds, but in carrying out acts tending to conceal or disguise their unlawful origin. Without that purpose, there is no offence.
Along the same lines, among others, STS 1080/2010, of 20 October; 858/2013, of 19 November; 809/2014, of 26 November; 408/2015, of 8 July; and 165/2016, of 2 March — the latter with a dissenting opinion arguing for absorption by the predicate offence.
STS 642/2018, of 13 December, consolidates the teleological restriction: where self-laundering involves a double disvalue, real concurrence cannot be applied cumulatively and blindly, rendering conduct involving an irrelevant amount atypical.
STS 833/2023, of 15 November, reiterates the non-typicality of self-laundering conduct involving an insignificant amount.
Why this matters for successive laundering: if the defendant is the same person already convicted for the original laundering, the charge under art. 301.2 CP over the subsequent transformations must pass a double test: that of non bis in idem with respect to the previous conviction, and that of the autonomous requirement of concealing intent in each new operation. Recycling the same facts under a different label is not a new offence.
4. Proving successive laundering: the triple circumstantial pillar and its limits
In cases of laundering linked to drug trafficking it is exceptional for the predicate offence to have been clarified and adjudicated. Hence the evidence is almost invariably circumstantial. And in successive laundering the problem multiplies: the more transformations and the more time that has elapsed, the more fragile each link becomes.
The consolidated triple pillar
STS 292/2024, of 22 March — rendered in cassation against a judgment of the 2nd Section of the Criminal Chamber of the Audiencia Nacional — recapitulates the consolidated case law (citing, among others, STS 693/2015, of 12 November; 703/2016, of 14 September; 724/2020; 725/2020; and 854/2022, of 27 October) on the triple circumstantial pillar that supports a conviction for laundering proceeds of an offence against public health:
Unjustified increases in wealth or anomalous financial transactions.
The absence of lawful economic, professional or business activities that would explain that income.
A link to illicit drug trafficking activities.
STS 645/2023, of 25 July (Reporting Justice: Excmo. Sr. D. Antonio del Moral García, appeal 4523/2021) expands the catalogue of indicators habitually relied upon: the significance of the amount laundered, the link between the perpetrators and illicit activities or persons connected with them, how unusual or disproportionate the increase in wealth is, the nature of the transactions — notably the intensive use of cash — and the absence of any lawful justification for the income.
But circumstantial evidence is not a lesser standard of proof
This is the core argument for the defense, and the one that case law formulates most forcefully: the fact that laundering can be proven through circumstantial evidence does not mean it is an offence of mere suspicion. As STS 645/2023 itself recalls, admitting circumstantial evidence does not relax the evidentiary requirements; it is simply another route to reach the same degree of objective certainty beyond all reasonable doubt required for any criminal conviction.
The requirements for the validity of a circumstantial inference were systematised in STS 444/2014, of 9 June (Reporting Justice: Excmo. Sr. D. Cándido Conde-Pumpido Tourón), in line with Constitutional Court doctrine: a plurality of indicators, each proven by direct evidence, their mutual interrelation, the rationality of the link, and the exclusion of reasonable alternative hypotheses.
The burden of establishing traceability rests entirely on the prosecution
In successive laundering, that requirement translates into something very concrete: the prosecution must reconstruct a chain of relationships — direct or indirect — between the successive transformation operations, showing how each one leads to the next. It is not enough to prove the starting point (the predicate offence) and the end point (the current estate) and presume the intermediate route.
💡 THE GOLDEN RULE OF DEFENSE
Every link the prosecution fails to document is a link that breaks the chain. If, between operation B and operation D, operation C is not proven, the contamination does not reach D: it reaches only as far as the evidence goes. Cross-examination of the financial expert — usually the author of a police asset-analysis report — should be aimed at identifying the logical gaps in the report, not at disputing its overall conclusions.
5. The most overlooked front: limitation periods, exhaustion and the dies a quo
There is a widespread claim in popular legal writing that "however much time has passed, the assets remain the proceeds of crime." As a slogan, it is appealing. As a legal statement, it is materially incorrect, and it is worth dismantling, because one of the most profitable defense lines depends on it.
Money laundering is not a continuing offence
STS 707/2006, of 23 June, established this clearly: laundering cannot be treated as a continuing offence, because if it were, it would never become time-barred — every concealment operation is, by definition, intended to be permanent. That same ruling, however, clarifies that where there are clearly differentiated successive transformations, the dies a quo may be set at the last relevant transformation.
Completion and exhaustion are not the same thing
STS 893/2013, of 22 November, resolves a particularly illustrative case: the sale of a property acquired with illicit funds seventeen years later. The prosecution argued that the conduct had not been exhausted and that the transfer reactivated the offence. Both the Provincial Court and the Supreme Court rejected that thesis: the offence was completed when the money was integrated into the legal circuit, and the illegality cannot be revived years later by a simple transfer of the asset.
Unless there is proven continuing activity
Conversely, STS 120/2013, of 20 February, found continuing laundering activity over several years through successive real-estate transactions designed to introduce funds in stages. There, the conduct had not been exhausted and the limitation period did not run while the organised, repeated activity persisted.
⚠️ THE DECISIVE TEST
The difference between STS 893/2013 and STS 120/2013 is not one of calendar time: it is one of structure. The question is not "how much time has passed?" but "are we looking at a single already-completed laundering operation whose effects continue, or at a plurality of autonomous operations introducing funds in stages?"
The prosecution will tend to describe the estate as a continuous, indivisible process, because that shifts the dies a quo to the last known transaction. The defense must break up the narrative: isolate each operation, fix its date of completion, and identify which ones were completed outside the time limit under Article 131 CP. In cases spanning twenty or thirty years — such as STS 299/2021 itself — this exercise is not incidental: it can drastically reduce the scope of the proceedings.
6. Tax havens, non-cooperative jurisdictions and opacity of the beneficial owner
Successive laundering finds its natural habitat in opaque jurisdictions, for a purely instrumental reason: they break the documentary traceability that the prosecution needs to reconstruct.
What an opaque jurisdiction technically contributes to the chain
Territories traditionally classified as tax havens are characterised by low or non-existent taxation and by scant or non-existent transparency regarding tax information. Their two classic operational uses for the launderer are:
Bank accounts protected by secrecy, structured through numbered codes that dissociate the identity of the real account holder.
Commercial companies with anonymous shareholders, formally administered by local agents resident in the territory itself, shielded by professional secrecy.
Today, second-generation vehicles must be added to this list: trusts and fiduciary structures, chains of companies with interposed fiduciary administrators, and conversion into crypto-assets as an additional layer of dissociation.
From the concept of "tax haven" to lists of non-cooperative jurisdictions
The category is today regulatory, not colloquial. Both the OECD and the European Union maintain lists of non-cooperative territories for information-exchange purposes, and Spanish law has replaced the old closed list with the concept of a non-cooperative jurisdiction, updated by regulation.
The exit criterion remains essentially the same: a territory ceases to have that status once a double-taxation treaty with an information-exchange clause or a specific tax information exchange agreement signed with Spain to that effect becomes applicable.
📋 A TECHNICAL NUANCE NOT TO BE MISSED
Three concepts that the prosecution tends to conflate must be kept separate: tax avoidance (lawful), tax evasion (which may constitute an offence under art. 305 CP) and money laundering (art. 301 CP). The fact that funds have passed through an opaque jurisdiction proves opacity, not criminal origin by itself. Opacity is an indicator; it is not the predicate offence. And without a proven predicate offence — even if only circumstantially, in its essential features — there is no laundering, whether original or successive.
The current hook: the EU's anti-money-laundering package and AMLA
The preventive landscape is undergoing a full transformation, and this directly affects the evidentiary material that will reach the courts in the coming years:
Regulation (EU) 2024/1624 (AMLR), of 31 May 2024, entered into force on 9 July 2024 and will be fully applicable from 10 July 2027, establishing a single rulebook directly applicable in the 27 Member States, which will prevail over national law in the event of conflict.
It is accompanied by Directive (EU) 2024/1640 (AMLD6), on institutional mechanisms, central registers and supervision, and Regulation (EU) 2024/1620, which creates AMLA (the Anti-Money Laundering Authority), headquartered in Frankfurt and operational since July 2025.
The AMLR substantially widens the scope of obliged entities — expressly including legal professionals, crypto-asset service providers and even professional football clubs — and introduces a harmonised limit of 10,000 euros on cash payments across the Union. It should be recalled that in Spain the general limit currently in force is notably more restrictive.
Law 10/2010, of 28 April, on the prevention of money laundering, will have to be adapted to the institutional requirements of AMLD6 before that same date.
Translation for the criminal practitioner: the volume and granularity of the wealth-related information available to prosecutors will grow exponentially, particularly regarding beneficial ownership. Interposed corporate structures built under the previous regime will become progressively more fragile, and the register of beneficial ownership will become an ordinary source of evidence. Anticipating that scenario in the defense strategy — and in preventive advice — is no longer forward-looking: it is due diligence.
7. Comparative table: original laundering, successive laundering, handling stolen goods and concealment
One of the most frequent confusions in indictments is the indiscriminate classification of conduct that in fact corresponds to different offences, legal interests and penalties. This table summarises the boundaries:
| Criterion | Original laundering (art. 301.1 CP) | Successive laundering (art. 301.2 CP) | Handling stolen goods (art. 298 CP) | Concealment (art. 451 CP) |
|---|---|---|---|---|
| Material object | Assets coming directly from the prior criminal activity | Assets coming from a prior act of laundering or from participation in it | Proceeds of an offence against property or the socioeconomic order | Does not necessarily concern assets |
| Typical conduct | Acquiring, possessing, using, converting or transferring with a concealing purpose | Concealing or disguising nature, origin, location, destination, movement, rights or ownership | Helping those responsible to benefit from the proceeds, or receiving them for personal gain | Assisting the perpetrator after the offence, without having taken part in it |
| Intent to profit | Not required | Not required | Required (typical element) | Not required |
| Legal interest protected | Socioeconomic order and Administration of Justice | Socioeconomic order and Administration of Justice | Property | Administration of Justice |
| Authorship | May be the perpetrator of the predicate offence (self-laundering) or a third party | May be the original launderer or a third party unrelated to them | Necessarily someone other than the perpetrator of the prior offence | Necessarily someone other than the perpetrator of the prior offence |
Strategic note: downgrading the charge from laundering to handling stolen goods or concealment — where the facts allow it — is an under-used defense route. The penalties, and above all the confiscation regime, differ substantially.
8. Defense checklist against a charge of successive laundering
☐ Identify and audit the predicate offence. Is there a final conviction? Is it identified with its essential features? Without evidence — even circumstantial — of the prior criminal activity, there is no material object of the offence. Also verify that the conduct is punishable under our legal system if the facts occurred abroad.
☐ Reconstruct the chain and locate the missing links. Prepare your own asset timeline, operation by operation. Mark every transformation the prosecution asserts but does not document. Those gaps are the focus of the report.
☐ Fix the date of completion of each operation and calculate the limitation period. Apply the STS 893/2013 vs. STS 120/2013 test: a single completed operation with continuing effects, or a plurality of staged operations? Invoke STS 707/2006 against any construction of laundering as a continuing offence.
☐ Individualise each client's intent. Challenge any charge built on membership of a family, corporate or professional circle. Recall the acquittal handed down in STS 299/2021 for lack of conclusive circumstantial evidence.
☐ Subject the financial expert report to effective cross-examination. Request the full supporting documentation, contrast the flow-imputation criteria used, and detect double counting, expenditure presumptions and unjustified extrapolations.
☐ Verify non bis in idem. If there is a prior conviction for the original laundering, check that the facts now charged constitute autonomous operations with their own concealing purpose, and not a reformulation of facts already adjudicated.
☐ Explore alternative classification. Consider whether the facts fit handling stolen goods (art. 298 CP) or concealment (art. 451 CP), or whether they are non-typical due to insignificance under STS 642/2018 and 833/2023.
☐ Scrutinise undue delays. Cases of successive laundering are structurally lengthy. Time the periods of inactivity from the opening of proceedings and raise the mitigating circumstance — highly qualified where appropriate — as recognised in STS 299/2021.
☐ Audit the scope of the confiscation. Verify that the ruling identifies the specific assets and their link to the activity, challenging any automatic extension to uncontaminated family assets.
9. Frequently asked questions about successive laundering
▶ What is successive money laundering?
It is the conduct defined in Article 301.2 of the Criminal Code consisting of concealing or disguising the nature, origin, location, destination, movement, rights over or ownership of assets that have already been the object of a prior act of laundering. It is called "laundering of what has already been laundered" because the conduct does not concern the direct proceeds of the predicate offence, but assets that were already transformed in a prior laundering operation.
▶ Can someone who did not take part in the original laundering be convicted of successive laundering?
Yes. Identity of authorship is not a requirement of the offence. Several different launderers may act on the same unlawful source, at successive points in time. However, for each participant, knowledge of the criminal origin of the assets — even on the basis of dolus eventualis — or gross negligence under Article 301.3 CP must be proven individually.
▶ Does the offence of money laundering become time-barred?
Yes. The Supreme Court has expressly ruled out treating laundering as a continuing offence (STS 707/2006, of 23 June), precisely because that construction would make it imprescriptible. The limitation period begins to run from the completion of each operation, understood as the effective integration of the funds into legal circulation. STS 893/2013 confirmed that the transfer of an asset many years after its acquisition with illicit funds does not reactivate an already-completed offence.
▶ Is it enough to prove that the estate is unjustified in order to convict for laundering?
No. The consolidated triple circumstantial pillar — unjustified increases in wealth, the absence of lawful activity to explain them, and a link to the prior criminal activity — is a method of proof, not a shortcut. Case law insists that laundering is not an offence of mere suspicion, and that circumstantial evidence must reach the same degree of certainty beyond all reasonable doubt required for any criminal conviction, excluding reasonable alternative hypotheses.
▶ Are the returns generated by a laundered asset also contaminated?
That is the thesis put forward by the prosecution, relying on the doctrine of transitive contamination: the laundered asset remains contaminated and contaminates whatever derives from it, including fruits, returns and subrogated assets while the structure remains operative. The defense must demand that this propagation be proven link by link and not presumed, and verify in each case whether the concealing purpose required by the offence is present.
▶ Is having a company in a tax haven a money-laundering offence?
Not by itself. The use of an opaque jurisdiction proves opacity, not the criminal origin of the funds. It is a relevant indicator that must be weighed together with the others, but it does not replace proof of the predicate offence or of the concealing purpose. It is important to draw a careful distinction between tax avoidance, tax evasion — potentially an offence under Article 305 CP — and laundering under Article 301 CP.
▶ What is the difference between successive laundering and self-laundering?
These are categories that operate on different planes. Self-laundering concerns the identity between the perpetrator of the predicate offence and the launderer, and its punishability was settled by the Resolution of the Non-Jurisdictional Plenary Session of the Second Chamber of 18 July 2006 and the reform under Organic Law 5/2010. Successive laundering concerns the material object: assets coming from a prior laundering operation, regardless of who committed it. Both may occur simultaneously, in which case both the non bis in idem control and the requirement of an autonomous concealing purpose in each operation must be satisfied.
Conclusion: the chain breaks at the link nobody documented
Successive laundering is, probably, the offence in the Criminal Code where the greatest distance exists between the expansive potential of the offence and the real capacity to prove it. The doctrine of transitive contamination allows illegality to be projected over entire estates and across decades; but that projection is only legitimate if the prosecution reconstructs, operation by operation, the route from the predicate offence to the seized asset.
The technical defense in these cases is not fought in the closing argument about the origin of the money. It is fought much earlier: in the asset timeline, in cross-checking the expert report against its supporting documentation, in the individualised calculation of the limitation period for each operation, and in individualising each defendant's intent. Where the prosecution builds a continuous narrative, the defense must return the case to its reality: a succession of specific acts, each with its date, its author and its evidence — or its absence.
10. Legal sources cited
All rulings are identified by number and date for location in the Judicial Documentation Centre (CENDOJ) of the General Council of the Judiciary.
| Ruling | Court / Reporting Justice | Matter decided |
|---|---|---|
| STS 299/2021, of 8 April (ROJ: STS 1236/2021 · ECLI:ES:TS:2021:1236) | TS, 2nd Chamber, 1st Section · Excmo. Sr. D. Javier Hernández García | Successive laundering through instrumental companies; transitive contamination; evidentiary difficulties; undue delays; closure of company and confiscation |
| STS 982/2021, of 15 December | TS, 2nd Chamber · Excmo. Sr. D. Vicente Magro Servet | Laundering in combination with forgery of a commercial document over assets linked to a prior conviction for laundering |
| STS 292/2024, of 22 March | TS, 2nd Chamber | Triple circumstantial pillar in laundering of proceeds from an offence against public health |
| STS 645/2023, of 25 July (appeal 4523/2021) | TS, 2nd Chamber, 1st Section · Excmo. Sr. D. Antonio del Moral García | Circumstantial evidence; laundering is not an offence of suspicion; catalogue of indicators |
| STS 833/2023, of 15 November | TS, 2nd Chamber | Non-typicality of self-laundering of an irrelevant amount |
| STS 642/2018, of 13 December | TS, 2nd Chamber | Teleological restriction of real concurrence in self-laundering |
| STS 165/2016, of 2 March | TS, 2nd Chamber | Punishability of self-laundering; synthesis of case-law development (with dissenting opinion) |
| STS 265/2015, of 29 April | TS, 2nd Chamber | Requirement of concealing purpose; limits on the punishment of self-laundering |
| STS 444/2014, of 9 June | TS, 2nd Chamber · Excmo. Sr. D. Cándido Conde-Pumpido Tourón | Requirements for the validity of circumstantial evidence |
| STS 893/2013, of 22 November | TS, 2nd Chamber | Completion and exhaustion; a later transfer does not reactivate a time-barred offence |
| STS 120/2013, of 20 February | TS, 2nd Chamber | Continuing laundering activity through staged real-estate transactions |
| STS 801/2010, of 23 September | TS, 2nd Chamber | Catalogue of indicators in the offence of laundering |
| STS 707/2006, of 23 June | TS, 2nd Chamber | Laundering is not a continuing offence; dies a quo in successive transformations |
| Resolution of the Non-Jurisdictional Plenary Session of the 2nd Chamber TS of 18 July 2006 | Supreme Court | Art. 301 CP does not, in every case, exclude real concurrence with the predicate offence |
Applicable legislation: Articles 127 et seq., 298, 301 to 304, 305, 451 and 570 bis and ter of the Criminal Code · Organic Law 5/2010, of 22 June · Law 10/2010, of 28 April, on the prevention of money laundering and terrorist financing · Directive (EU) 2018/1673 · Regulation (EU) 2024/1624 (AMLR) · Directive (EU) 2024/1640 (AMLD6) · Regulation (EU) 2024/1620 (AMLA).
Methodological note: the rulings cited are presented in doctrinal paraphrase. Before invoking any of them in a procedural document, it is recommended to check the full text and transcribe the relevant legal grounds literally from CENDOJ, as well as to verify their continued validity and any later case law.